


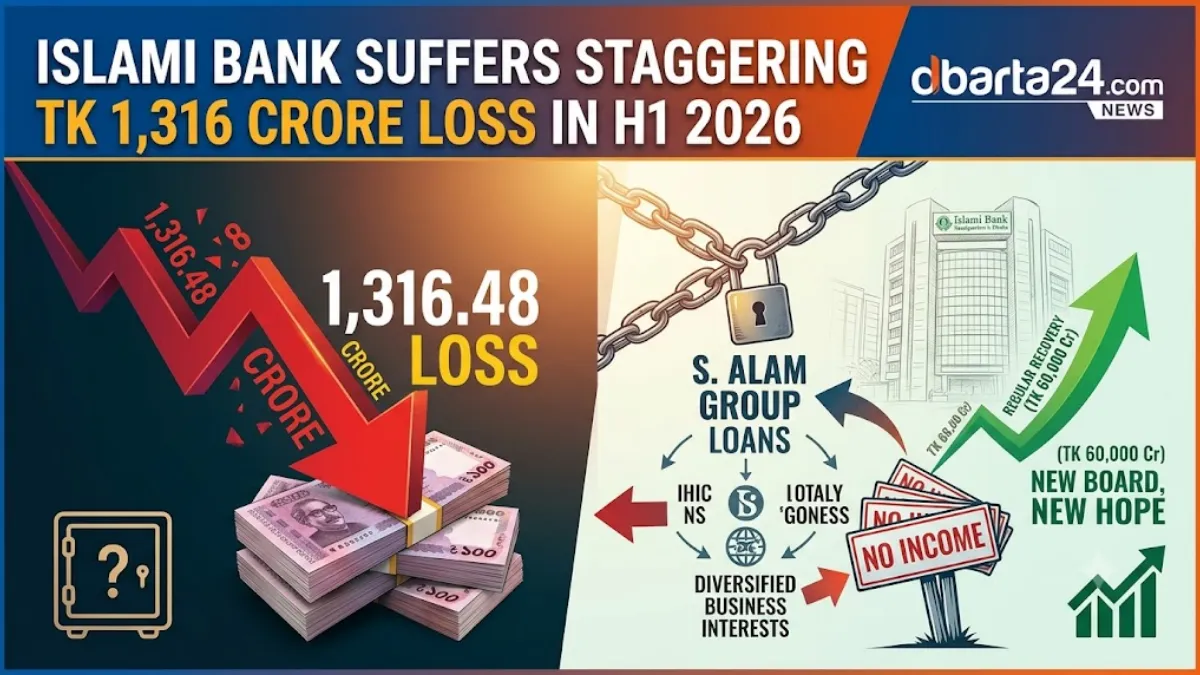
M K Alam,Dbarta24 — Islami Bank Bangladesh PLC has registered a staggering consolidated net loss of Tk 1,316.48 crore during the first six months (January–June) of 2026.
This marks a monumental collapse in the bank’s financial health compared to the same period last year, when it posted a net profit of Tk 67.40 crore.
The financial performance indicators were made public following a board of directors meeting held at the bank’s headquarters on Wednesday (29 July).
Quarterly Breakdown and EPS Erosion
According to the bank’s half-yearly financial disclosures, the consolidated earnings per share (EPS) plummeted to a negative Tk 8.10 for the January–June period.
The bank’s financial slide accelerated drastically as the year progressed:
-
Q1 (January–March): The bank initially booked a loss of Tk 288 crore.
-
Q2 (April–June): Losses swelled dramatically by an additional Tk 1,028.26 crore.
On a standalone basis—excluding the performance of its subsidiaries—Islami Bank’s solo net loss reached Tk 1,326.81 crore, resulting in a standalone EPS of negative Tk 8.24.
This downward spiral breaks a consecutive five-year streak of profitability, which saw the bank record net profits of Tk 635.33 crore in 2023, Tk 108.78 crore in 2024, and Tk 136.34 crore in 2025.
Toxic Loans and Higher Deposit Costs Fuel the Deficit
The management of Islami Bank attributed this historic deficit to rising costs associated with profit payouts to depositors, a decline in investment income due to soaring non-performing loans, and reduced returns from funds parked in other banks.
The core of the crisis lies in heavily concentrated toxic credit. Speaking on the condition of anonymity, a senior executive of the bank revealed that a massive volume of loans remains trapped with the conglomerate S. Alam Group.
While the bank generates zero income from these stuck investments, it must regularly honor its commitments and pay out profits to its depositors.
“Out of our total deposit base of approximately Tk 1.62 lakh crore, regular cash recovery is being generated from only Tk 60,000 crore,” the senior official stated.
Confirming the systemic bottleneck, Islami Bank’s Acting Managing Director, Md. Altaf Hossain, stated:
“A vast amount of investment is trapped in a large industrial conglomerate, yielding no income for the bank. Conversely, we have to sustain the profit payouts to our depositors. This imbalance has pushed the bank into a loss.”
Recovery Measures and Strategic Outlook
To navigate out of the severe liquidity crunch, bank officials believe that specialized policy intervention from the central bank is crucial.
Suggestions include forming an Asset Management Company (AMC) via Bangladesh Bank initiatives or allowing a fraction of the unrecovered loans to be moved off-balance sheet through a special regulatory framework.
Despite the bleak mid-year ledger, the bank’s management cited early signs of a turnaround.
The senior official noted that around Tk 500 crore in fresh deposits entered the bank over a two-day period.
Management remains optimistic that the formation of a reconstituted board of directors will successfully restore customer trust and stabilize operations going forward.